Fast, Secure, and Convenient: Exploring India's Leading Payment Platforms
- Filed by
- Business
- Received
- Length
- 2 min
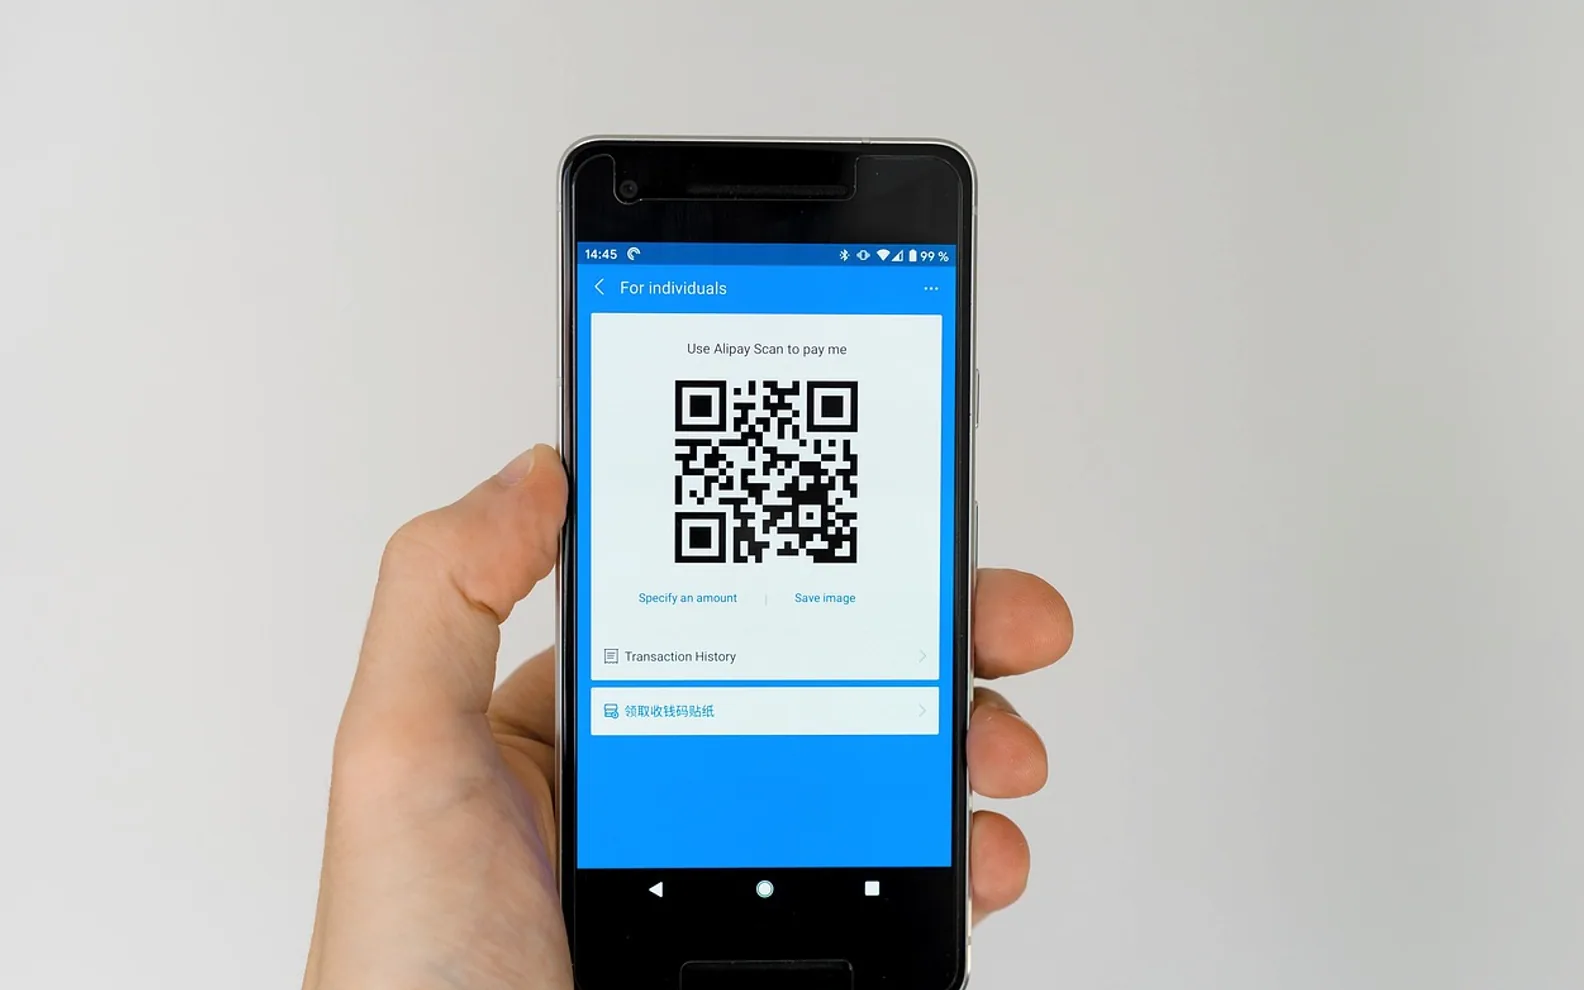
Buy a cup of tea from a roadside stall in an Indian city and there is a good chance the vendor will point at a printed QR code before mentioning cash. That small scene sums up how deeply digital payments have settled into daily commerce. Phones have become wallets, and settling a bill often takes less time than counting change.
The building blocks behind the speed
Several rails run side by side, and each has its place:
| Method | Typical use | What people like about it |
|---|---|---|
| Unified Payments Interface | Person-to-person transfers, shop payments via QR | Works across banks and apps with a simple ID |
| Mobile wallets | Small purchases, recharges, bill payments | Quick checkout and familiar interfaces |
| Cards | Online shopping, travel, larger purchases | Wide acceptance and purchase protections |
| Net banking | Tax, tuition, business invoices | Direct link to the account for formal payments |
The common thread is interoperability. A customer using one bank can pay a merchant whose account sits with a different bank, through yet another app, without either side needing to think about it.
Why UPI attracts attention abroad
The Unified Payments Interface has become a reference point in conversations about real-time payments far beyond India. Travellers, students and business visitors from other countries frequently look it up before a trip; Chinese-speaking readers searching for 印度upi can find an orderly explanation of how the system links bank accounts, apps and merchant QR codes. That curiosity is easy to understand, since the model shows how a shared public infrastructure can support many competing apps at once.
What small businesses gain
For a neighbourhood grocer or a tailor, the appeal is practical. A printed code costs almost nothing to display, payments arrive in the bank account rather than a cash drawer, and the transaction history doubles as a simple sales record. That record can later support conversations with a lender or an accountant, because income is documented rather than estimated.
Larger merchants add payment gateways that accept every method at checkout, so customers can pick whatever they trust most. Subscription services, utilities and transport operators have followed the same route.
Staying safe while paying quickly
Speed brings its own risks, and most fraud depends on persuading people to act in a hurry. Small routines that protect you:
- Never share a PIN or one-time password, whoever claims to be asking.
- Remember that receiving money never requires entering a PIN; a request to do so is a warning sign.
- Check the payee name shown in the app before confirming.
- Download payment apps only from official app stores and keep them updated.
- Report a suspicious transaction to the bank straight away.
Used with that care, India's payment platforms deliver on the three promises in their name: they are quick, they are protected by layered checks, and they fit neatly into ordinary routines from the morning commute to the evening shopping run.
- 70
- articles
- 10
- topics
- 2
- min average read
- 2020–2026
- years covered