The Risks of Bridge Loans in the UK and How to Avoid Them
- Filed by
- Finance
- Received
- Length
- 2 min
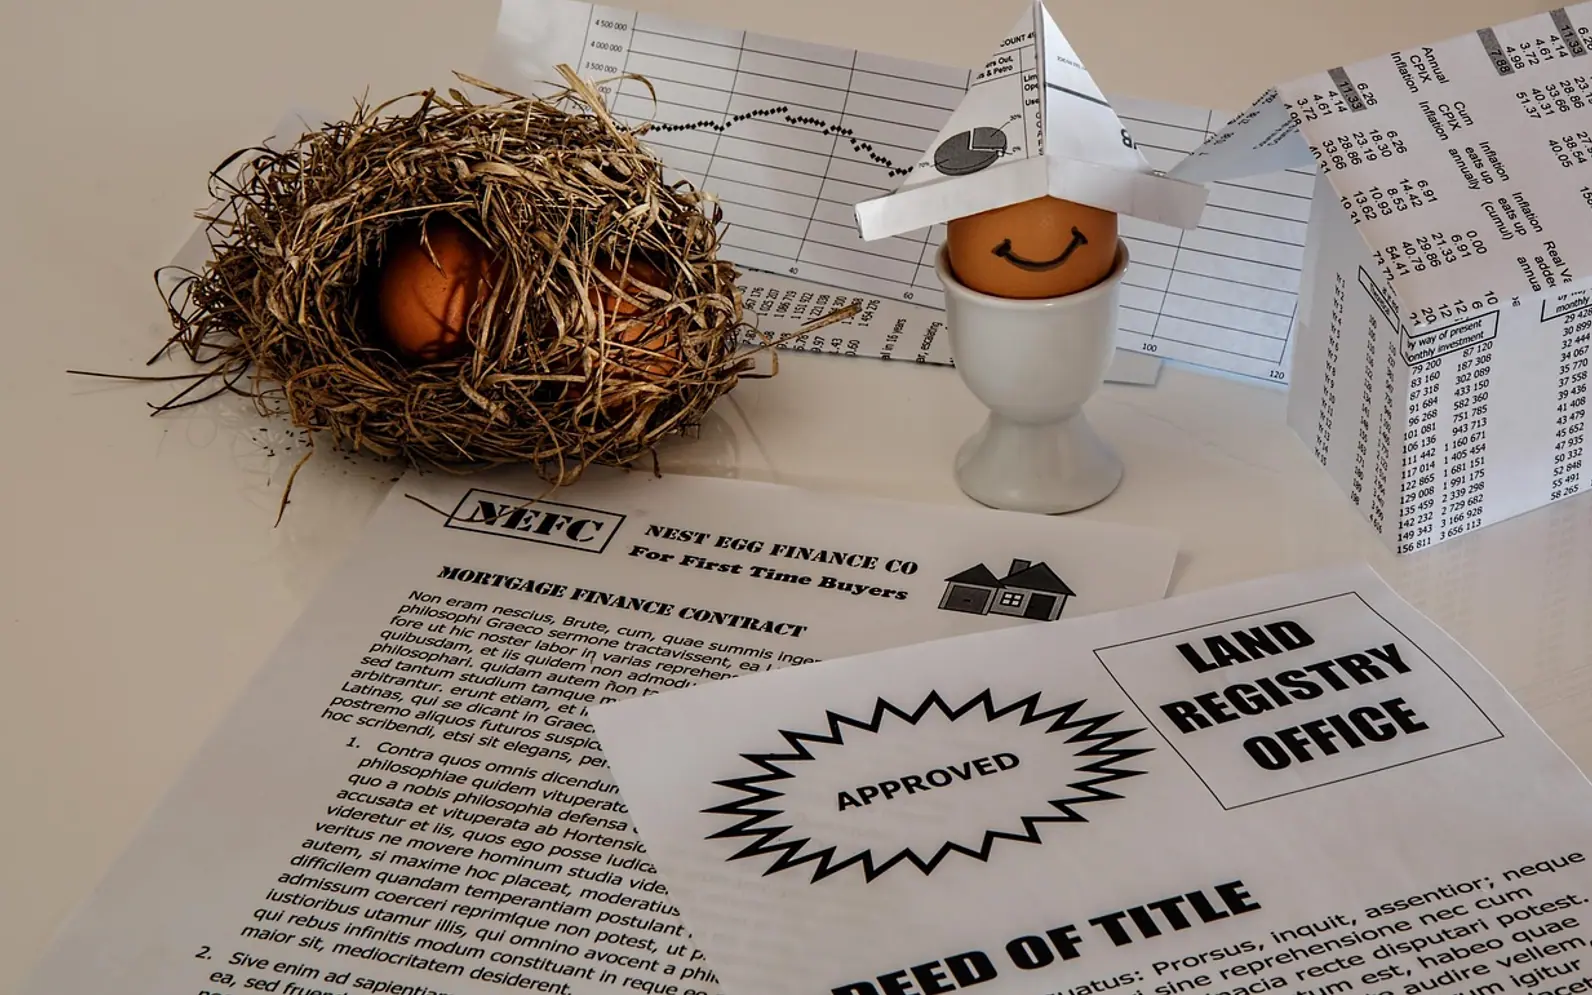
Bridging loans exist to solve timing problems. A buyer wants to lock in the next home while the current one is still on the market, an auction purchase must complete within weeks, or a renovation project needs funds before a mortgage lender will lend on it. The speed is real, but so is the pressure: the loan is short, secured on property and expected to be repaid in full at the end of the term. Understanding where things go wrong is the best protection.
The exit is the whole plan
Every bridging loan is repaid by an event: a sale, a remortgage or another source of funds. If that event is delayed or falls through, the borrower faces default interest, extra fees and, in the worst case, the lender selling the property to recover its money.
Reducing the risk: write down the exit route, its realistic timeline and what would happen if it took twice as long. Keep a second option in mind, such as a lower asking price or an alternative lender for refinancing, and contact the lender early if delays appear.
Costs that add up quickly
Interest on bridging finance is usually charged monthly and is typically higher than on a standard mortgage. On top come arrangement fees, valuation and legal costs, broker fees and sometimes exit fees. Interest may be retained or rolled up, which means the amount owed grows over the term even without monthly payments.
Running the figures before applying turns these costs into something concrete. A bridging loan calculator UK borrowers can use at the planning stage is handy here, because it shows how the loan amount, term and rate interact and makes it easier to compare scenarios side by side.
Valuation and loan-to-value
Bridging loans are secured on property, so the value placed on that property shapes everything. An optimistic estimate can lead to borrowing more than a quick sale would cover. If the market softens during the term, the margin shrinks further.
- Base plans on an independent valuation, not on asking prices nearby.
- Assume a sale may take longer and achieve less than hoped.
- Leave headroom by borrowing below the maximum offered.
Terms you might miss
Bridging agreements can include minimum interest periods, charges for extending the term and conditions that let the lender demand repayment in specific situations. Some loans are regulated, for example when the property is or will be the borrower's home, while many investment loans are not, which affects the protections available. Reading the full offer, including the default and extension clauses, is essential.
Getting proper advice
Because the stakes are high and every case differs, it makes sense to speak to an independent, appropriately authorised finance adviser and a solicitor before signing. They can check whether bridging is the right tool at all, compare it with alternatives and review the small print. A property used as security can be repossessed when repayments are missed, so a cautious plan, conservative numbers and a clear exit are worth far more than speed alone.
- 67
- articles
- 9
- topics
- 3
- min average read
- 2020–2026
- years covered